Local claim risks
- Hail
- Microbursts
- Wind-blown fences
- Frozen pipes
- Siding damage
Housing mix
2000s–2020s subdivisions, townhomes, retail centers
A newer housing stock with its own problems
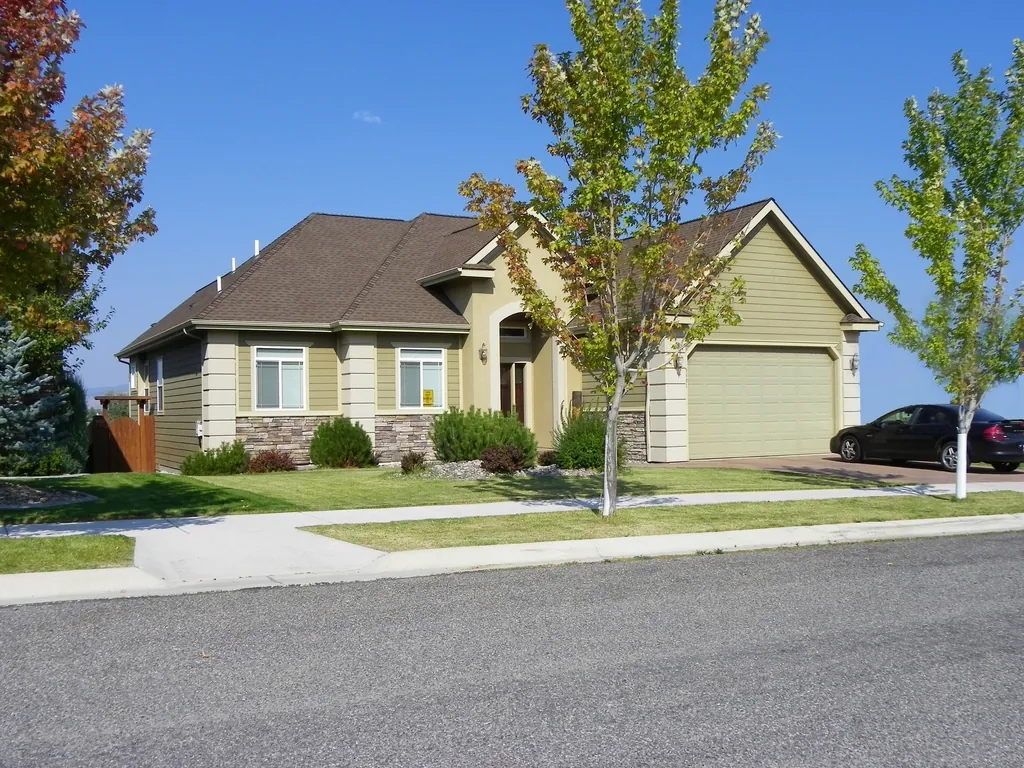
Most Meridian homes were built after 2000 in master-planned subdivisions such as Paramount, Bridgetower and the neighborhoods spreading south toward Kuna. That brings advantages, like modern codes, but also challenges. Builder-grade shingles and vinyl siding were installed in large batches, and many colors and profiles have since been discontinued. When a hail or wind storm damages one elevation, matching becomes the central dispute.
Open land around the city lets summer thunderstorms build quickly, and microbursts have flattened fences and stripped siding across whole blocks. Winter brings hard freezes that crack irrigation lines and supply lines in exterior walls.
Common Meridian claim disputes
- Repair-only estimates on roofs where the shingle line can’t be matched.
- One-elevation siding repairs that leave a visible mismatch.
- Fence claims capped under other-structures coverage.
- Townhome water losses that cross from one unit to another.
- Commercial roof claims on retail centers along Eagle Road and Fairview Avenue.
Serving all of Meridian
We work across Meridian, from the older homes near downtown to the subdivisions north of Chinden and south of I-84, plus the retail and office properties around The Village. As a Meridian insurance appraiser we can review the carrier’s estimate first, or start with an on-site inspection if the damage is ongoing.
Services for Meridian property owners
Every Idaho Insurance Appraiser service is available in Meridian and the surrounding area, including:
- Appraisal Clause Representation
- Homeowner Claim Appraisal
- Commercial, HOA & Farm Appraisal
- Roof & Hail Damage Appraisal
- Wind & Microburst Claim Appraisal
- Water & Frozen Pipe Appraisal
- Fire & Smoke Damage Appraisal
- Wildfire Claim Appraisal
Questions for a Meridian Insurance Appraiser
Hail hit my whole subdivision. Do I need my own appraiser?
Each policy is separate, so each owner has their own claim and their own appraisal rights. Neighbors’ results can be useful context, but your award depends on your property and policy.
My siding is discontinued. What can I expect?
That depends on your policy’s matching language and the specific damage. Document the mismatch with photos and manufacturer information, and ask the carrier to explain its position in writing.