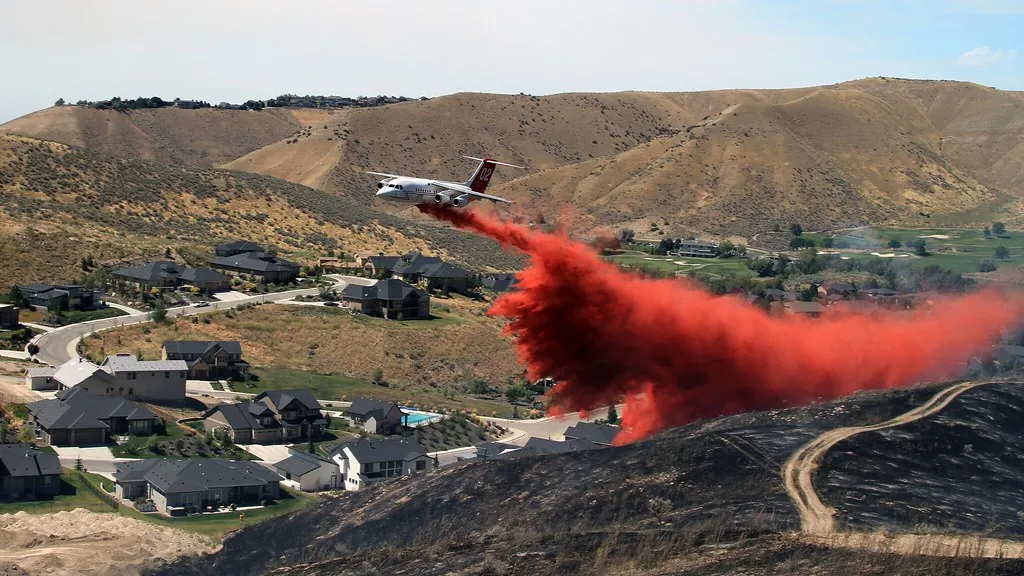
Wildfire is Idaho’s signature peril
Much of Idaho is public forest and rangeland, and more homes are built every year where those lands meet subdivisions. The state’s history is full of reminders: the Big Burn of 1910 swept across the Panhandle and through towns in the Silver Valley. In 2008 a wind-driven fire on Boise’s southeast bench destroyed ten homes. The 2013 Beaver Creek Fire forced evacuations in the Wood River Valley, and the 2016 Table Rock Fire burned through the foothills directly above Boise. Every summer, smoke from fires across the West settles into Idaho valleys.
Three kinds of wildfire claims
- Total losses. Rebuilding on a steep lot outside Hailey or Sandpoint costs more than a city tract home, and demand surges after a regional fire. Dwelling limits, extended replacement cost endorsements and code upgrades all come into play.
- Partial losses at the fire’s edge. Ember-ignited decks, melted siding, scorched fences and heat-cracked windows, often with smoke inside.
- Smoke-only claims for homes that never saw flame. Whether these are covered, and how much cleaning is needed, are among the most disputed questions in wildfire claims.
Where wildfire claim appraisal adds value
We build an independent rebuild estimate that reflects site access, local labor and materials, and current code, including any wildland-urban interface requirements your county or city has adopted. For smoke claims we review testing and document residue in HVAC systems, attics and soft goods. For contents we help structure an inventory the panel can work from.
If you’ve just been through a fire
Photograph everything you can safely reach, keep every receipt for evacuation and living expenses, and request a certified copy of your policy. Don’t discard damaged items until the carrier has documented them.
Questions about wildfire claim appraisal
Is smoke damage from a distant wildfire covered?
Many policies cover smoke damage from a hostile fire, but carriers sometimes dispute whether residue amounts to physical loss. The answer depends on the policy and the evidence. Testing results and documentation matter.
My rebuild cost exceeds my dwelling limit. Can appraisal help?
Appraisal can establish the full amount of loss, but it can’t raise your policy limit. Extended replacement cost endorsements and other coverages may provide more. Check your declarations page.
Do I have to rebuild on the same lot?
Many policies allow rebuilding elsewhere or taking a payout, with conditions. Read the loss-settlement terms and ask the insurer to confirm its position in writing.